This free roth ira calculator checks whether your income keeps you eligible for 2026, works out your exact allowed contribution with the phase out math, and shows what you can take out tax free under the IRS ordering rules. No signup, everything runs in your browser.
Roth IRA calculator
2026 IRS limits built in. Pick a mode, everything runs in your browser.
Estimate for planning only. 2026 Roth IRA limits: $7,500 under 50, $8,600 at 50+. IRS ordering rules: contributions come out first, then conversions, then earnings.
Quick answer
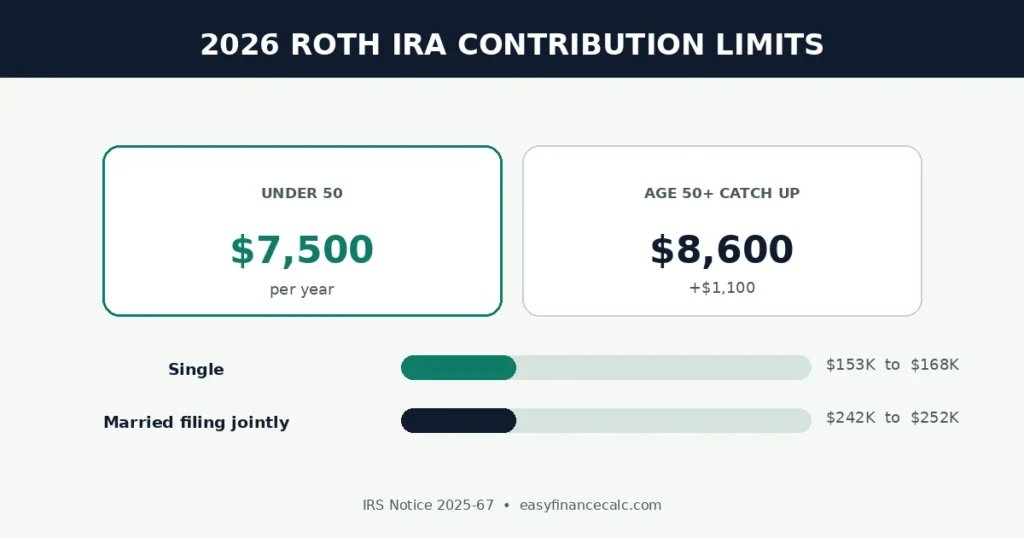
A Roth IRA is an individual retirement account you fund with after tax dollars. Qualified withdrawals in retirement are tax free. For 2026 you can contribute up to $7,500, or $8,600 if you are 50 or older, as long as your income falls under the IRS phase out ranges.
How to Use This Roth IRA Calculator
Two modes, one tool. Wondering where to begin? Start with the mode that matches your question.
- Check your limit. Pick Limit mode and enter filing status, MAGI, age, and earned income. A roth ira contribution calculator with an eligibility check matters, because an ineligible contribution triggers a 6% penalty every year it sits there.
- Plan a withdrawal. In Withdraw mode, enter your balance, lifetime contributions, first contribution year, and age, and the roth ira withdrawal calculator applies the ordering rules to show what comes out tax free.
Quick note on names. Search results also call this an ira calculator roth or an ira roth calculator. Same rules either way: after tax money in, tax free money out when you follow the IRS rules. Whether you searched for an ira calculator roth or a roth ira contribution calculator, the steps work the same. An ira roth calculator with eligibility built in is the kind worth trusting. Call it an ira calculator roth or an ira roth calculator. The rules do not care.
What Is the Roth IRA Contribution Limit for 2026?
The Roth IRA contribution limit for 2026 is $7,500 under 50, and $8,600 at 50 or older. The catch up amount rose from $1,000 to $1,100 and is now indexed to inflation. Figures from IRS Notice 2025-67, which is why this roth ira calculator 2026 page can be trusted over rivals still showing 2025 numbers.
| 2026 | |
|---|---|
| Under 50 | $7,500 |
| Age 50 or older | $8,600 |
| Monthly pace to max it | $625, or $716.67 at 50+ |
| Deadline for 2026 contributions | April 15, 2027 |
Two catches: the limit is shared across all IRAs, and you cannot contribute more than your earned income. So how do income limits layer on top? See the phase out table.
Roth IRA Income Limits 2026: The Phase Out Table
Earn too much and the IRS shrinks your direct Roth contribution. These are modified adjusted gross income (MAGI) ranges for 2026.
| Filing status | Full contribution below | Phase out range | None at or above |
|---|---|---|---|
| Single or head of household | $153,000 | $153,000 to $168,000 | $168,000 |
| Married filing jointly | $242,000 | $242,000 to $252,000 | $252,000 |
| Married filing separately, lived with spouse | $0 | $0 to $10,000 | $10,000 |
Inside a range, your allowed amount shrinks proportionally. Single with $160,000 MAGI? You are $7,000 into a $15,000 range, so you lose about 47% and can contribute roughly $4,000. A good roth ira contribution calculator applies this formula automatically. Too rich for direct contributions? That is what the backdoor Roth is for, covered below.
Roth vs Traditional IRA: The Tax Treatment
Forget projections. The Roth versus Traditional choice is a tax bill choice, and you can settle it with two multiplications. Take the same $7,500 contribution. In a Traditional IRA, a 22% bracket saves you $1,650 of tax today, and every dollar you withdraw in retirement is taxed as income. In a Roth IRA, you pay that $1,650 today, and qualified withdrawals in retirement are taxed at $0. Same contribution, opposite tax timing. A roth vs traditional ira calculator is really comparing tax timing.
| Roth IRA | Traditional IRA | |
|---|---|---|
| Tax today | After tax, no deduction | Deductible if eligible |
| Tax in retirement | Qualified withdrawals tax free | Withdrawals taxed as income |
| 2026 limit | Shared $7,500 / $8,600 cap | Shared $7,500 / $8,600 cap |
| RMDs | None, ever | Start at 73 |
| Early access | Contributions anytime, tax and penalty free | 10% penalty before 59 and a half |
Roth wins when your retirement tax rate will exceed today's, because you lock in the lower bill now. Traditional wins when today's bracket is higher than the future bill. Flexibility breaks ties: Roth has no RMDs, and contributions can come back out anytime. If you have a workplace plan, the Traditional deduction phases out at $81,000 to $91,000 single and $129,000 to $149,000 jointly for 2026, above which Roth usually wins outright. Our Roth IRA vs Traditional IRA guide walks through the tax bill comparison in full.
The Two 5 Year Clocks (Do Not Mix These Up)
The most misunderstood Roth rule. There are two separate 5 year clocks.
Clock 1: the earnings clock. Starts January 1 of the tax year of your first Roth IRA contribution, and never resets. Contribute for tax year 2026 in April 2027? Your clock started January 1, 2026. Once it has run 5 years AND you are 59 and a half, earnings come out completely tax free.
Clock 2: the conversion clock. Every Roth conversion starts its own 5 year clock. Withdraw converted principal within 5 years while under 59 and a half and you owe a 10% penalty on it. Example: convert $20,000 in 2026 at 55, withdraw it in 2028 at 57, penalty is $2,000. Wait until 2031 and it is zero.
The Withdraw mode asks for your first contribution year to apply Clock 1. A roth ira withdrawal calculator that ignores the clocks can call a withdrawal tax free when it is not.
Backdoor Roth IRA and the Pro Rata Rule
Over the income limit? The backdoor Roth is the legal workaround: contribute to a Traditional IRA without deducting, then convert to Roth. A roth ira conversion calculator can estimate the tax, and a roth ira conversion tax calculator multiplies the taxable portion by your marginal rate. But beware the pro rata rule.
The IRS treats all your Traditional, SEP, and SIMPLE IRAs as one account. Example: $92,500 pre tax in a rollover IRA plus a $7,500 nondeductible contribution, then convert $10,000. Only 7.5% is tax free ($750). The other $9,250 is taxable. Before converting, run a roth ira conversion calculator that asks about existing pre tax balances, because the pro rata math changes everything.
The fix: roll pre tax IRA money into your 401(k) first, leaving only after tax dollars in the IRA. Then the conversion is nearly tax free. Converting in a low income year shrinks the bill further, which is why a roth ira conversion tax calculator should let you test different years. Report it on Form 8606.
Roth IRA Withdrawal Ordering Rules
Withdrawals come out in a fixed order: contributions first, then conversions, then earnings.
Example: $40,000 in contributions, $10,000 converted, $25,000 of earnings, $75,000 total. The first $40,000 out is always tax and penalty free, at any age. The next $10,000 follows the conversion clock. Only the last $25,000 of earnings faces tax plus the 10% penalty if taken early. A roth ira withdrawal calculator showing this three bucket split turns an abstract rule into a plan.
5 Mistakes That Shrink Your Roth IRA
- Funding but never investing. Contributions sit in a settlement fund until you invest them. An uninvested Roth is a savings account. Check that money is actually invested after you fund the account.
- Contributing while ineligible. Over the MAGI limit with no backdoor plan means a 6% excise tax every year the excess stays. A roth ira contribution calculator with an eligibility check prevents exactly this.
- Forgetting the shared limit. Roth plus Traditional share one $7,500 or $8,600 cap. Split across accounts without tracking and you will overcontribute.
- Ignoring the pro rata rule. Converting for a backdoor Roth while holding pre tax IRA balances makes most of the conversion taxable, as shown above.
- Using stale limits. Some ranking pages show 2025 figures ($7,000 and $8,000, $150,000 to $165,000 phase outs) labeled as 2026. The 2026 numbers are $7,500, $8,600, $153,000 to $168,000, and $242,000 to $252,000, verified against IRS Notice 2025-67. A roth ira calculator 2026 page that cannot get the year right is not worth trusting.
Frequently Asked Questions
How much can I contribute to a Roth IRA in 2026?
$7,500 under 50, $8,600 at 50 or older, capped at earned income and shared across all IRAs. Deadline: April 15, 2027.
What if my income is too high for a direct Roth contribution?
Use the backdoor Roth: nondeductible Traditional IRA contribution, then convert. Clear pre tax IRA balances into a 401(k) first to dodge the pro rata rule, and report on Form 8606.
Is a Roth IRA better than a Traditional IRA?
Higher rate in retirement favors Roth; lower favors Traditional. Run a roth vs traditional ira calculator with your own rates before deciding.
Can I contribute to a Roth IRA if I also have a 401(k)?
Yes. Separate systems, separate limits. In 2026 you can do the full Roth IRA amount plus your full 401(k) contribution.
When can I withdraw from a Roth IRA without penalty?
Contributions: anytime, tax and penalty free. Conversions: after their 5 year clock, or after 59 and a half. Earnings: tax and penalty free at 59 and a half once the earnings clock has run 5 years.
Do Roth IRAs have required minimum distributions?
No. Roth IRA owners never face RMDs at any age, a major edge over Traditional IRAs and 401(k)s.
What happens if I contribute too much?
A 6% excise tax for every year the excess remains. Withdraw the excess plus earnings before your filing deadline to fix it.
How do I actually do a backdoor Roth?
Contribute to a Traditional IRA without deducting, then convert, ideally within days. A roth ira conversion tax calculator gives you the honest cost once existing balances are entered.
Can I use my Roth contributions as an emergency fund?
Yes. Contributions come out tax and penalty free, so some planners say young savers should max the Roth before building a separate emergency fund. Unused annual space is gone forever.
Does funding a Roth IRA mean I am investing?
No. Funding fills the account; you must still invest the cash. Check that your money is working, not sitting in settlement.
What is the Roth IRA 5 year rule?
Two clocks: one earnings clock from January 1 of your first contribution year, and a separate clock per conversion. Mix them up and an early withdrawal can surprise you.
Should I convert my Traditional IRA to a Roth?
It fits low income years or when filling a low bracket. A roth ira conversion calculator estimates the bill. Conversions are irreversible since 2018, so model first.
Related calculators
Run the roth ira calculator above with your own numbers, then pair it with the rest of the cluster.
- 401k Calculator
- Retirement Withdrawal Calculator
- Roth IRA vs Traditional IRA guide
- All retirement calculators
Disclaimer
Estimates for planning only, not tax or investment advice. IRS limits and phase out ranges change yearly. Confirm eligibility and tax details with a qualified professional.