Standard vs Itemized Deductions: Which Saves You More in 2026
Every tax return asks one question first: do you take the standard deduction or do you itemize? Standard vs itemized deductions is not a permanent choice. You pick fresh every year, and the right pick is simply whichever number is bigger. For 2026, that means comparing $16,100, $32,200, or $24,150 against your own deductible expenses.
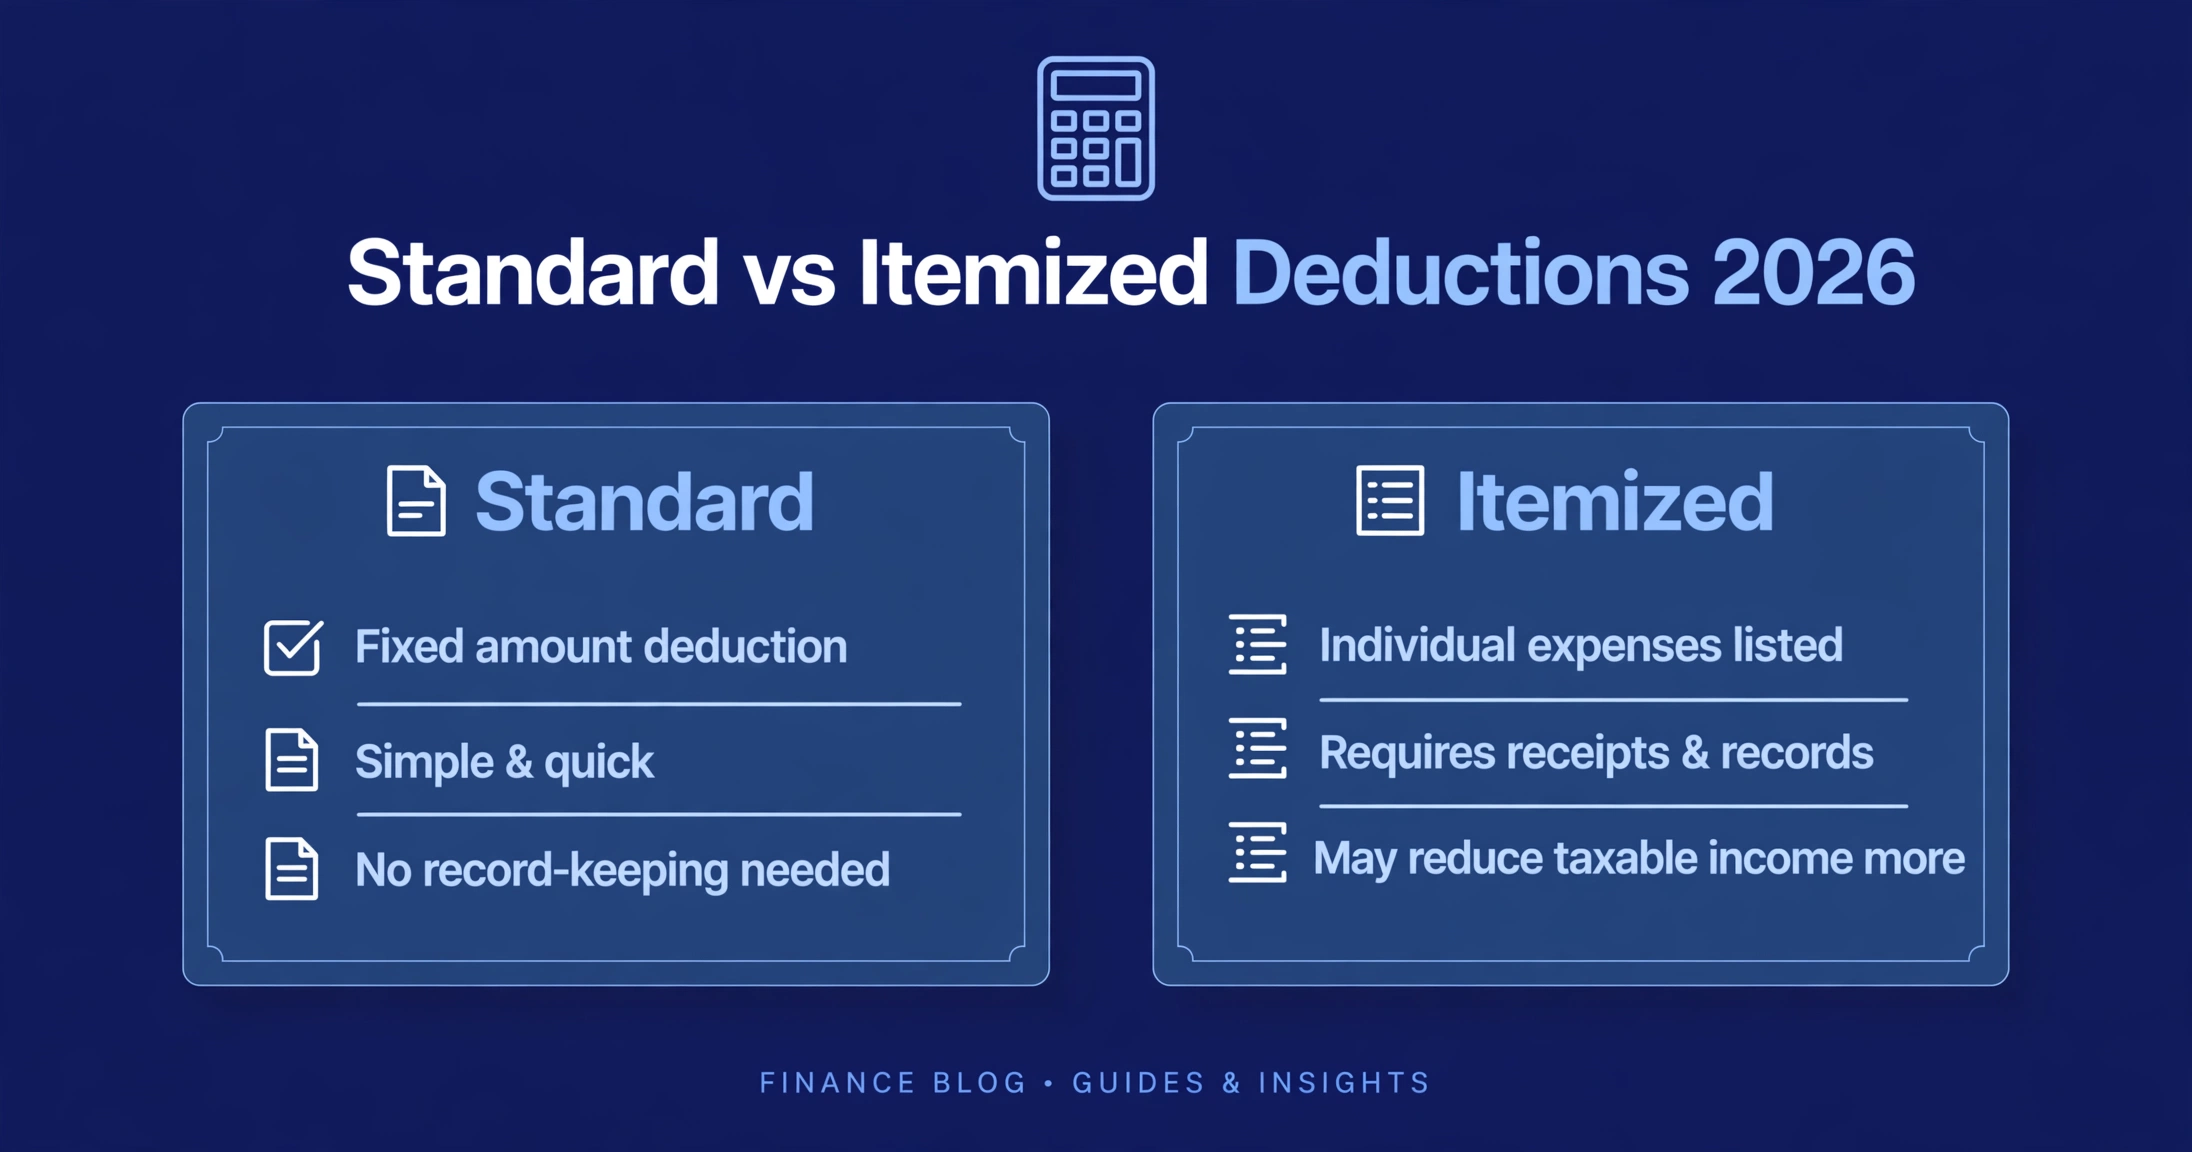
Here is the short version. The standard deduction is a fixed amount set by the IRS, based on your filing status. Itemizing means adding up your own deductible expenses, things like mortgage interest, state and local taxes, charity, and medical bills, and claiming that total instead. You cannot claim both. So which one saves you more in 2026? The one with the bigger number, and this guide shows you how to work it out in about ten minutes.
What Is the Standard Deduction?
The standard deduction is a flat amount that lowers your taxable income with no receipts, no worksheets, and no questions. For tax year 2026 the amounts are $16,100 for single filers and for married couples filing separately, $32,200 for married couples filing jointly, and $24,150 for heads of household. Those figures come from the IRS 2026 inflation adjustments, and they apply to the return you file in early 2027.
Two groups get a larger standard deduction. If you are age 65 or older, or blind, you add $2,050 if you file single or as head of household, or $1,650 per qualifying spouse on a joint return. So a married couple where both spouses are 65 or older starts at $35,500 before anything else, which raises the bar itemizing has to clear.
Most taxpayers take the standard deduction, and that is not laziness, it is math. The standard amounts are high enough now that a typical renter with modest charity and no mortgage rarely beats them. If your itemized total cannot beat your standard amount, taking the standard deduction is the correct move, and it also means far less paperwork.
What Counts as an Itemized Deduction?
Itemized deductions are the specific expenses Congress lets you subtract on Schedule A of your tax return. The big four cover almost every case, and it helps to know what each one actually includes.
First, mortgage interest. Interest you paid on a loan used to buy, build, or improve your main home or a second home generally counts, for acquisition debt up to $750,000, or $375,000 if you file separately, for loans taken out after December 15, 2017. Your lender sends you Form 1098 each January with the exact interest figure, so this one needs no guessing.
Second, state and local taxes, known as SALT. This bucket holds your property taxes plus either your state income taxes or your state sales taxes, whichever is larger. For 2026 the combined SALT total is capped at $40,400 for most filers, or $20,200 if you file separately. That cap is much higher than the old $10,000 limit, which is why itemizing is back on the table for many homeowners. The cap starts to shrink once your modified adjusted gross income passes $505,000, but it never falls below $10,000, and it is scheduled to drop back to $10,000 in 2030 unless Congress acts.
Third, charitable gifts. Cash gifts to qualified charities count in full, up to a percentage of your income that depends on the type of gift. Gifts of property, stock, or household goods have their own rules and need a receipt, and any single gift of $250 or more needs a written acknowledgment from the charity. Keep the receipts, because charity is the category the IRS asks about most.
Fourth, medical and dental expenses, but only the part above 7.5 percent of your adjusted gross income. If your adjusted gross income is $80,000, the first $6,000 of medical bills does not count at all, and only the amount above $6,000 goes on Schedule A. Health insurance premiums you pay with after tax dollars, dental work, and prescription costs can all count toward that total.
Smaller categories exist too, such as gambling losses up to your winnings, and certain casualty losses in a federally declared disaster area. For most people, though, the decision comes down to the big four, and if those four do not beat your standard deduction, nothing else will save the comparison.
How Do Standard vs Itemized Deductions Work?
The rule is simple, and it is the whole game. Add up every expense that qualifies on Schedule A. Compare that total with your standard deduction for your filing status. Claim whichever number is larger. That is it. There is no penalty for itemizing one year and taking the standard deduction the next, and there is no reward for loyalty to either choice.
One exception matters for married couples filing separately. If one spouse itemizes, the other spouse must itemize too, even if that spouse has almost nothing to deduct. That rule alone makes filing separately a bad deal for many couples, so check it before you split your returns.
Timing can also change the answer, and this is where a little planning pays off. Because you choose fresh each year, you can bunch expenses into one year when it helps. Paying two years of charitable gifts in December, or scheduling a planned medical procedure before year end, can push a borderline total over the standard deduction line in that year, while you take the standard deduction the next year. The expenses are real either way, you are just choosing which year they land in.
So how do you actually run the comparison? Gather four numbers: your mortgage interest from Form 1098, your property tax bills plus state income tax paid, your charitable receipts, and your medical total above the 7.5 percent threshold. Add them up, compare with the standard amount for your filing status, and the bigger number wins. The worked example below runs that exact comparison for a real household.
The 2026 Standard Deduction by Filing Status
| Filing status | 2026 standard deduction |
|---|---|
| Single | $16,100 |
| Married filing separately | $16,100 |
| Head of household | $24,150 |
| Married filing jointly | $32,200 |
| Extra, age 65 or older or blind, single or head of household | $2,050 per condition |
| Extra, age 65 or older or blind, married filing jointly | $1,650 per qualifying spouse |
That table is your target. Itemizing only makes sense if your Schedule A total beats the number in your row. A single renter needs more than $16,100 of qualifying expenses, which is a high bar without a mortgage. A married couple needs more than $32,200, which sounds high until a mortgage, property taxes, and charity stack up together.
Worked Example: Mark and Emily in Ohio
Mark and Emily file jointly and live in Ohio. Their 2026 numbers are straightforward, and they show exactly how the comparison works.
Their mortgage interest for the year is $14,500, straight from their Form 1098. Their property tax bill is $9,800, and their Ohio income tax paid is $6,200. Added together, their state and local taxes come to $16,000, which sits well under the 2026 SALT cap of $40,400, so the full $16,000 counts. They also gave $4,000 to charity during the year, with receipts for every gift.
Add it up: $14,500 plus $16,000 plus $4,000 equals $34,500 in itemized deductions. Their standard deduction as a joint couple is $32,200. Itemizing wins by $2,300. At their 22 percent marginal tax rate, that extra $2,300 of deductions saves them $506 in federal tax compared with taking the standard deduction. Not a fortune, but real money for an hour of record keeping.
Now move the same couple to New Jersey, where property taxes and state income taxes run much higher. Their mortgage interest is $19,000, their property tax is $18,000, and their state income tax is $15,000, for a SALT total of $33,000, still under the $40,400 cap, plus $6,000 in charity. Their itemized total is $58,000, which beats the $32,200 standard deduction by $25,800. At 22 percent, that is $5,676 saved. Same couple, same income, very different answer, and the only thing that changed is where they live and what they pay in taxes.
Contrast that with a single renter. Suppose you pay $4,500 in state income tax and give $800 to charity, with no mortgage and no property tax. Your itemized total is $5,300, while your standard deduction is $16,100. The standard deduction wins by $10,800, and itemizing would cost you money. This is why most renters, and many homeowners with small mortgages, take the standard deduction without a second thought.
5 Mistakes That Cost You Money
The first mistake is itemizing out of habit without running the numbers. Plenty of homeowners itemized for years when the SALT cap was $10,000 and their total still cleared the old standard deduction, then kept itemizing after the standard deduction rose past their total. Run the comparison every year, because the numbers move.
The second mistake is forgetting the SALT cap. People add up their full property tax and state income tax bills, get an exciting total, then learn at filing time that only $40,400 of it counts for 2026. Always apply the cap before you compare.
The third mistake is counting medical bills in full. Only the amount above 7.5 percent of your adjusted gross income counts. If your adjusted gross income is $80,000 and your medical bills are $9,000, only $3,000 goes on Schedule A, not $9,000.
The fourth mistake is filing separately without checking the spouse rule. If your spouse itemizes and you file separately, you must itemize too, even if your own total is tiny. That forced choice can easily cost more than whatever filing separately was supposed to save.
The fifth mistake is losing the receipts. Charity without a receipt, property tax without a bill, mortgage interest without Form 1098: the IRS can disallow any of them. A simple folder, paper or digital, with one document per deduction, is the difference between a deduction you keep and one you lose in an audit.
When Itemizing Clearly Wins
Itemizing usually wins in three situations. The first is a large mortgage in the early years of the loan, when most of each payment is interest and the Form 1098 figure is at its peak. The second is living in a high tax state, where property taxes plus state income taxes stack up fast under the higher $40,400 SALT cap. The third is a year with unusually large charity or medical bills, where bunching two years of gifts or one big procedure into a single year pushes the total over the line.
If none of those apply, the standard deduction is probably your answer, and that is fine. That comparison is the whole point of standard vs itemized deductions, and it is worth running every single year.
Frequently Asked Questions
What is the difference between the standard deduction and itemized deductions?
The standard deduction is a fixed amount set by the IRS based on your filing status: $16,100 single, $32,200 joint, or $24,150 head of household for 2026. Itemized deductions are your actual qualifying expenses, such as mortgage interest, state and local taxes, charity, and medical bills above 7.5 percent of your income, added up on Schedule A. You claim whichever total is larger.
How do I know whether to itemize or take the standard deduction?
Add up your qualifying expenses on Schedule A, remembering the $40,400 SALT cap for 2026 and the medical threshold of 7.5 percent of your income. Compare that total with your standard deduction for your filing status. If your itemized total is higher, itemize. If it is lower, take the standard deduction.
Can I switch between the standard deduction and itemizing every year?
Yes. You make the choice fresh on each tax return. Many people itemize in a year with a big mortgage interest bill or large charitable gifts, then take the standard deduction the next year when their expenses fall back. Nothing locks you into either choice.
Do I need receipts to itemize?
Yes, in practice. Keep Form 1098 for mortgage interest, property tax bills, state tax payment records, and charity receipts, including a written acknowledgment for any single gift of $250 or more. The IRS can ask for proof of any deduction you claim, and a deduction without a document is easy to lose.
Does the standard deduction change if I am 65 or older?
Yes. For 2026 you add $2,050 if you file single or as head of household, or $1,650 per qualifying spouse on a joint return, for age 65 or older or blindness. A joint couple where both spouses are 65 or older therefore starts at $35,500, which makes itemizing harder to justify.
What happens if my spouse itemizes and we file separately?
You must itemize too. When a married couple files separately, if one spouse itemizes, the other spouse cannot take the standard deduction. Check this rule before choosing to file separately, because it can wipe out the benefit you were hoping for.
Are property taxes fully deductible in 2026?
Property taxes are deductible only as part of the SALT bucket, which also includes your state income taxes or sales taxes. The combined SALT total is capped at $40,400 for most filers in 2026, or $20,200 if you file separately. If your combined state and local taxes exceed the cap, the excess gives you no deduction.
Can renters itemize deductions?
Yes, anyone can itemize if the total qualifies. Renters usually struggle to beat the standard deduction because they have no mortgage interest and no property tax, but large charitable gifts, high state income taxes, or big medical bills can still push a renter over the line in some years. Run the numbers before you assume the answer.
What counts toward itemized deductions?
The main categories are mortgage interest, state and local taxes up to the SALT cap, charitable gifts to qualified charities, and medical expenses above 7.5 percent of your adjusted gross income. Gambling losses up to your winnings and certain disaster losses can also count. Personal expenses like rent, groceries, and commuting costs never count.
Should I itemize if my total is only slightly above the standard deduction?
Usually yes, because even a small excess saves tax at your marginal rate. But weigh the extra paperwork and audit exposure. If the excess is only a few hundred dollars, bunching next year gifts or expenses into this year can widen the gap and make the choice clearly worthwhile.
Estimate Your Refund With the Right Deduction
Run your numbers through our free tax refund calculator and see what your deduction choice means for your refund.
Estimate Your RefundOnce you know which deduction wins, see what it means for your money. Our tax refund calculator estimates your refund with your deduction choice built in, our quarterly estimated taxes guide covers the payments self employed workers owe during the year, and our self employed tax deductions guide lists every write off that lowers income before the standard deduction even enters the picture. If withholding is your worry instead, our guide on how to fill out W-4 walks through every step. Standard vs itemized deductions is a choice you remake every year, and the habit that pays off is running the comparison before you file, not after. (Tax Calculators hub)
Disclaimer: This guide is for education only and is not financial, tax, or legal advice. Tax rules change, and your situation may differ from the examples here. Check the Schedule A instructions and the IRS publications listed below, and talk to a qualified tax professional before you act.
Sources: Internal Revenue Service, Revenue Procedure 2025-32, 2026 inflation adjustments. Internal Revenue Service, IR-2025-103, tax inflation adjustments for 2026. Internal Revenue Service, Schedule A instructions, itemized deductions. Internal Revenue Service, Publication 502, medical and dental expenses. Internal Revenue Service, Topic 503, deductible taxes.
By EasyFinanceCalc Team | Published October 29, 2026 | Last updated October 29, 2026
Written by Marcus
Tax editor at Easy Finance Calc, covering federal taxes, refunds, and credits.


One Comment